What the 10 Biggest VC Rounds in History Are Really Saying
The 10 largest VC rounds in history are reshaping the technology landscape with the rise of AI infrastructure.
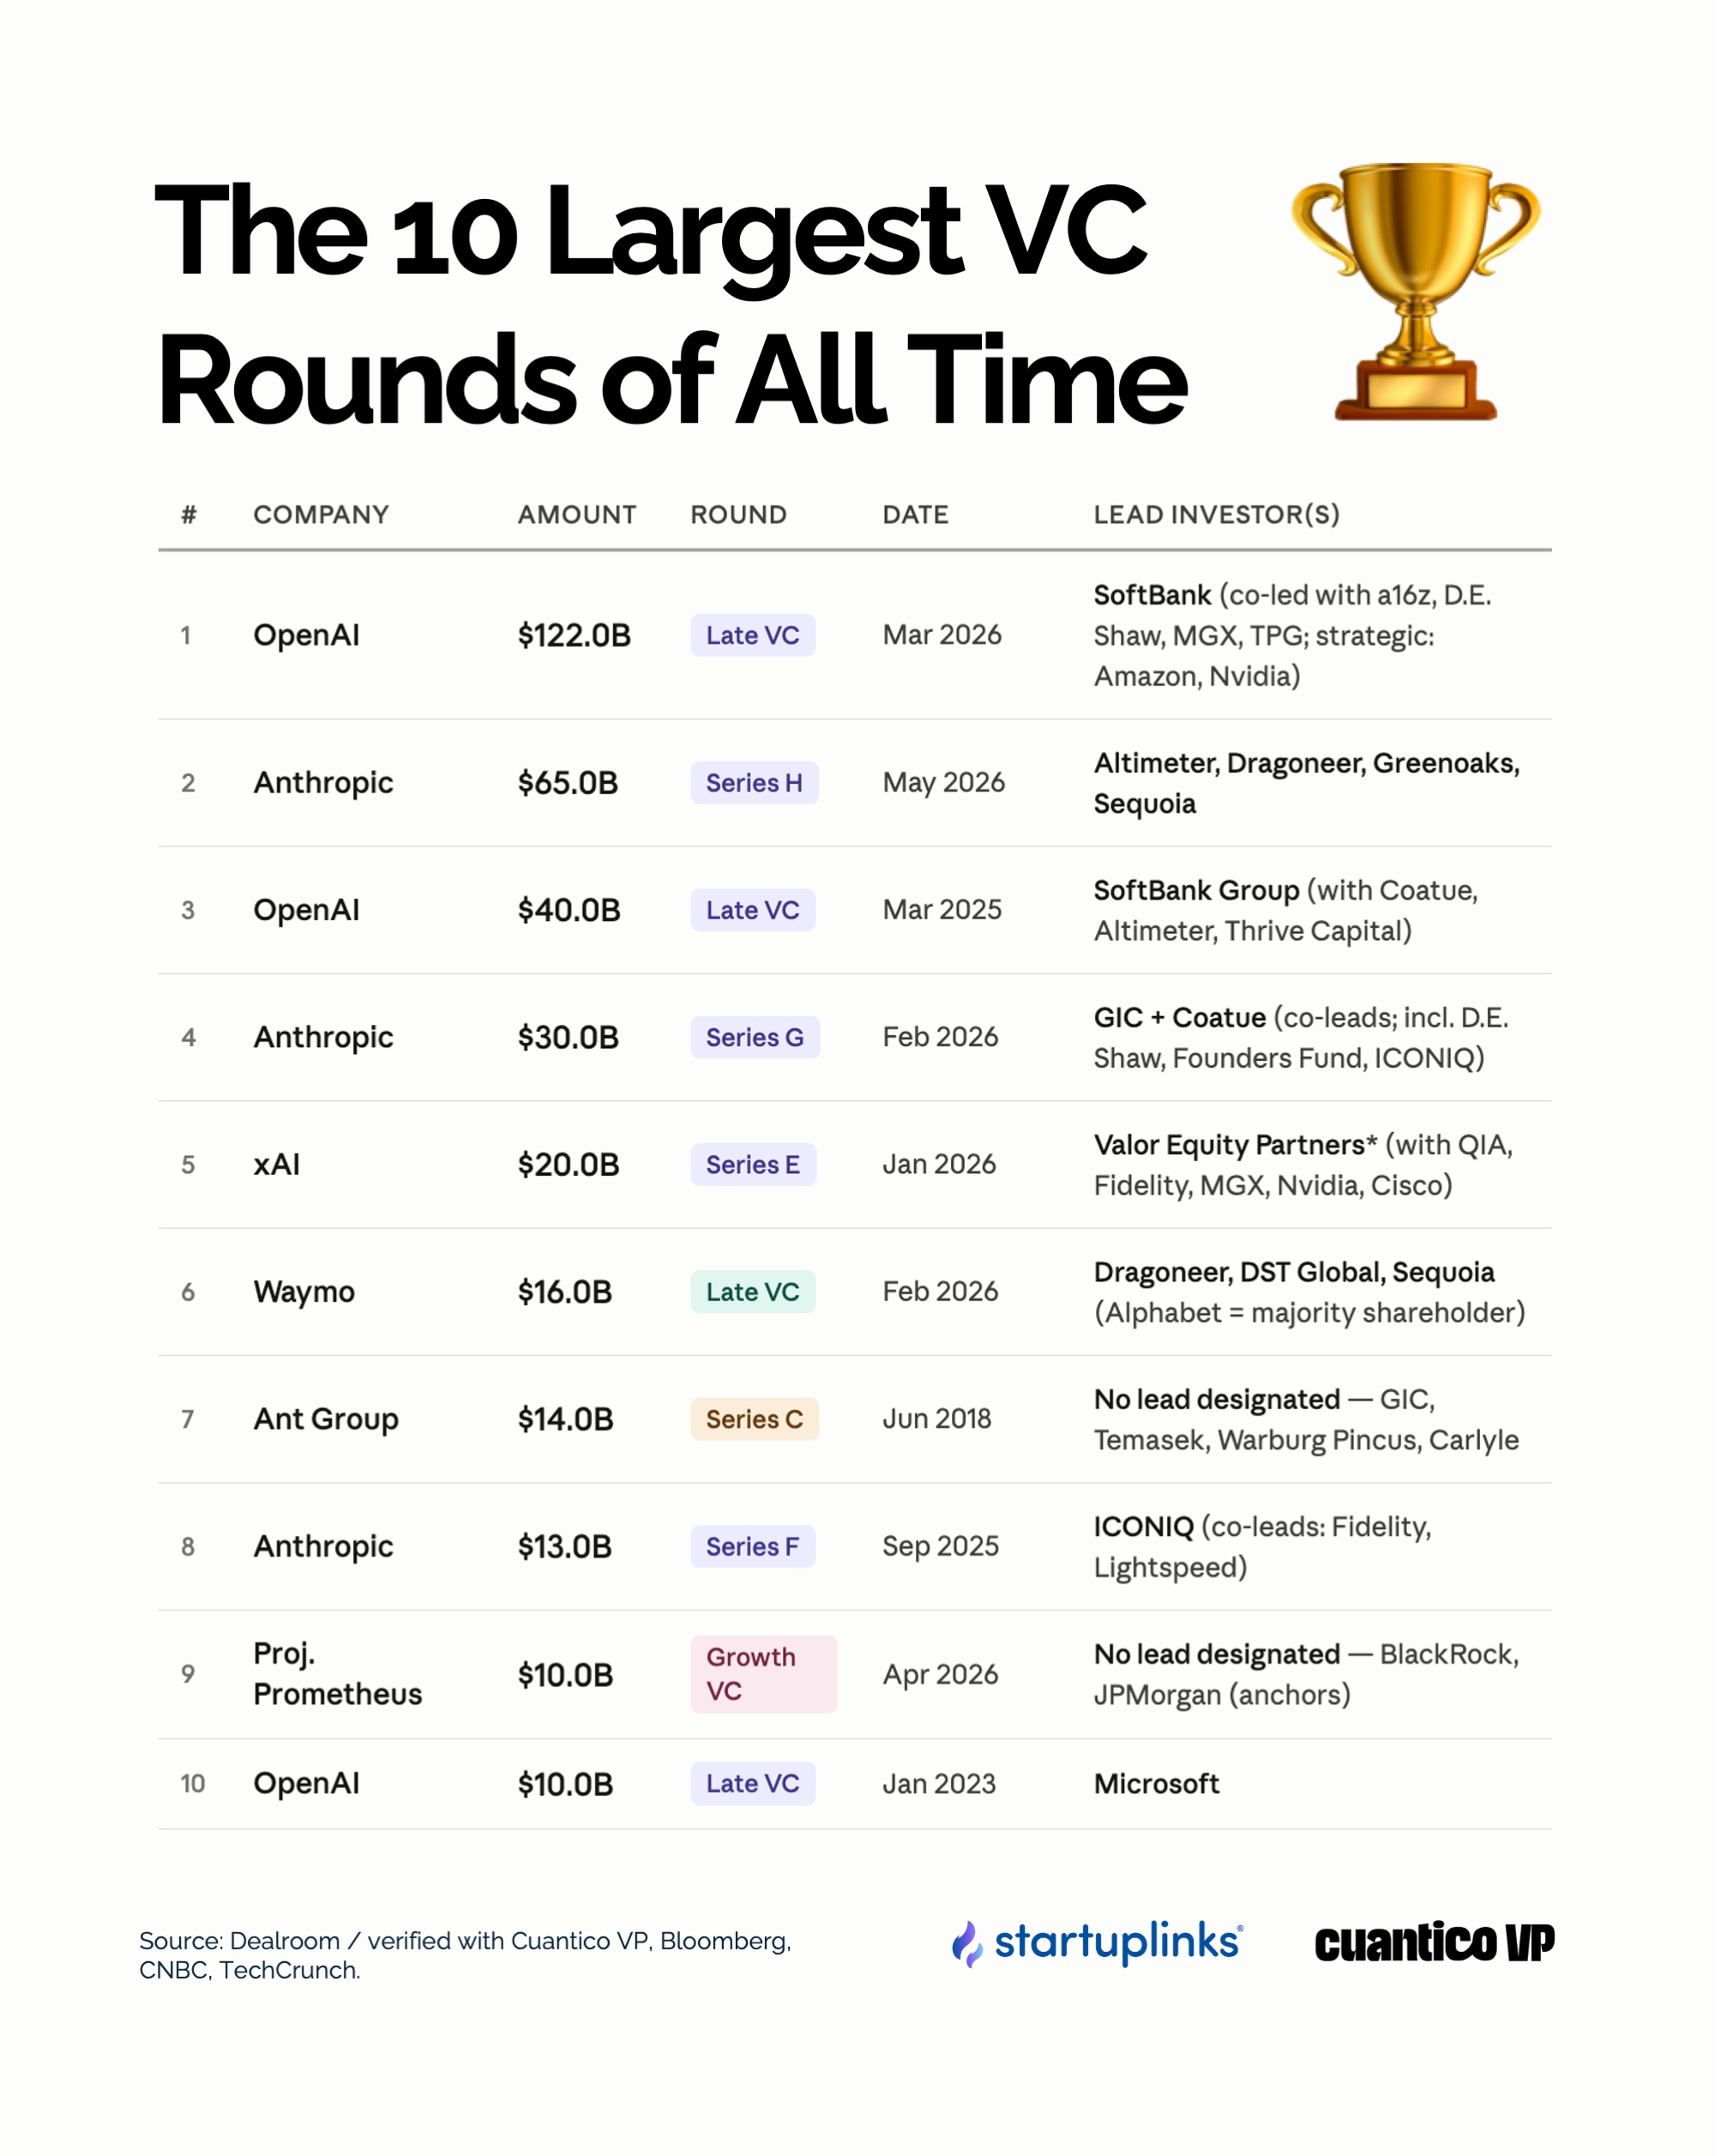
Over the past three years, we’ve seen something unprecedented in the history of venture capital: a single company, OpenAI, raising a $122B mega-round in 2026, another $40B round in 2025, and a “nontraditional” $10B round led by Microsoft in 2023; Anthropic appearing three times in the global top 10 with checks of US$13B, US$30B, and US$65B; and xAI, Waymo, Ant Group, and even an enigmatic “Project Prometheus” rounding out the list.
It’s a ranking that looks like a scoreboard from another galaxy, but behind those figures is something far more important than the shock of the numbers themselves. Each round reveals how the relationship between capital, infrastructure, and technological power is being rewritten on a global scale. And it’s right there that the following insights converge—insights that almost no one has noticed, revealed in recent research by Cuantico VP, a leading Venture Intelligence firm specializing in emerging markets.
1. SoftBank Is Building an AI Infrastructure Monopoly, Not Just Placing Bets
There’s a fundamental difference between betting on who will win a race and building the highway everyone will have to travel on. Masayoshi Son, SoftBank’s legendary and controversial founder, chose the second option.
SoftBank led or co-led OpenAI’s two largest rounds: the US$122B round in March 2026 and the US$40B round in March 2025. In total, it committed around US$60B to that company alone. SoftBank controls ARM Holdings, the chip designer whose architecture is found in virtually all mobile devices and increasingly in AI accelerators. It also co-founded Stargate, the AI infrastructure project in the United States that committed up to $500B for data centers and advanced computing.
What emerges is an unprecedented position: SoftBank has exposure to the world’s most widely used language model (OpenAI), the chips that process that intelligence (ARM), and the infrastructure that hosts it (Stargate). If AI becomes the new electricity, SoftBank is building the distribution network. The question is no longer whether OpenAI will win or lose. The question is: can anyone operate in AI without relying on some SoftBank asset?
2. Anthropic: The Fastest-Growing Company in the History of Private Capital
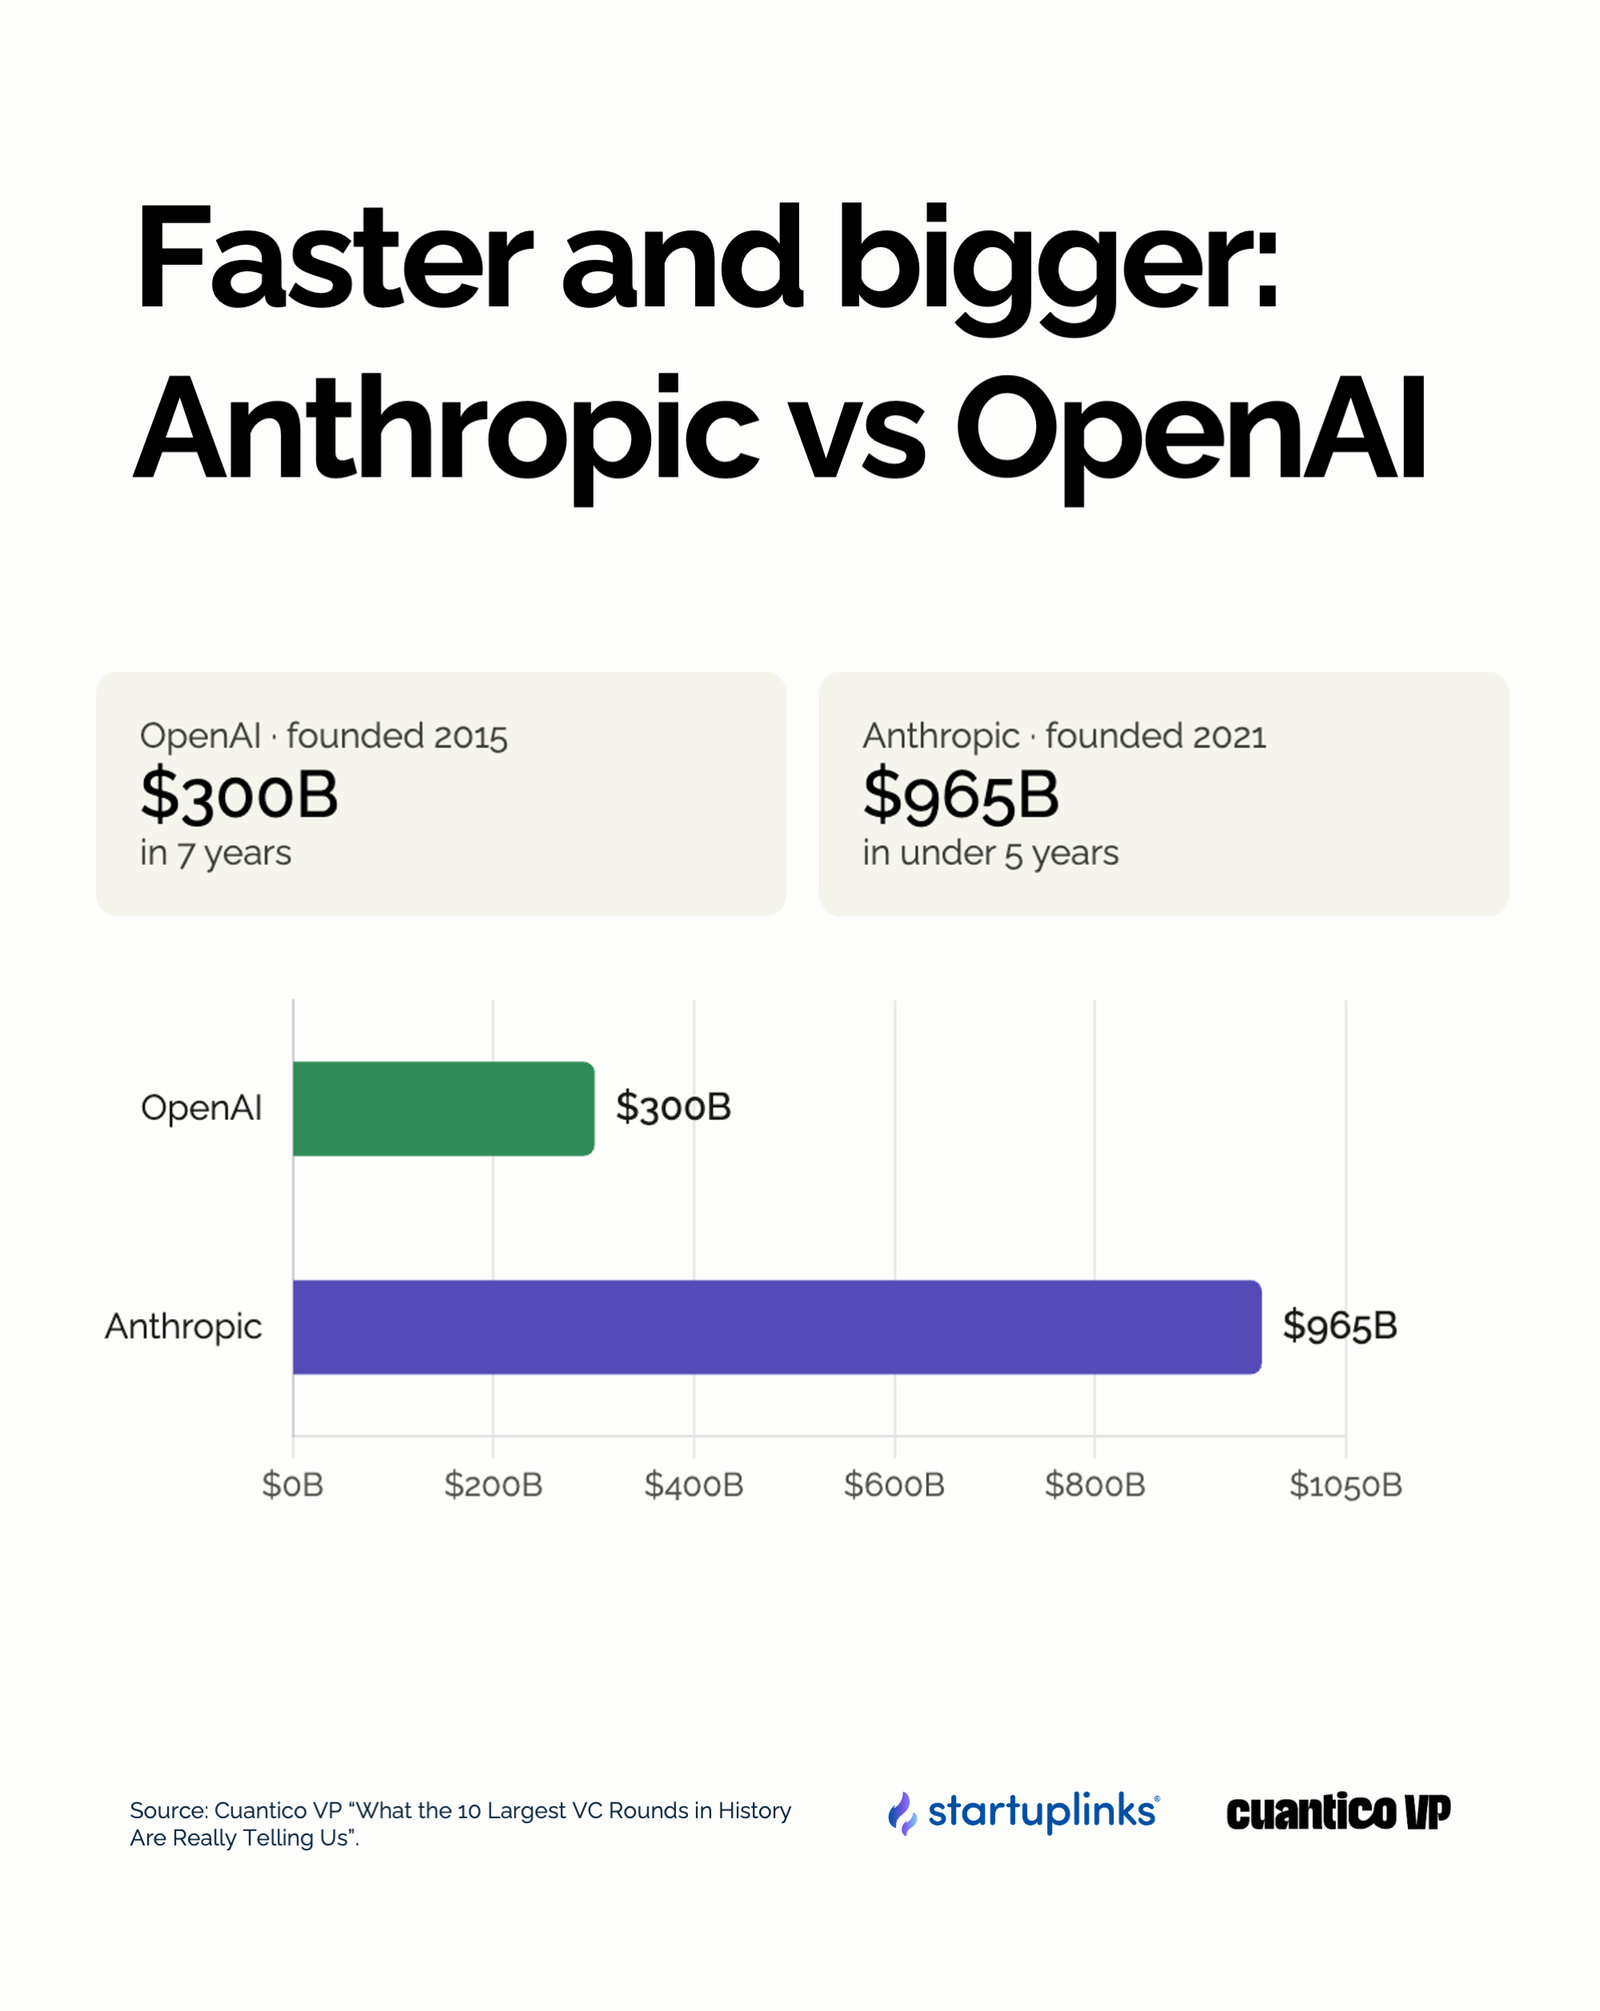
Historical comparisons are difficult, but this one is impossible to ignore. OpenAI, founded in 2015, took seven years to reach a US$300B valuation. Anthropic, founded in 2021, closed its Series H in May 2026 at a US$965B valuation—in other words, it came close to a trillion dollars less than five years after its founding.
Beyond the speed of its valuation growth, it’s important to look at its revenue growth. At the time of the Series H announcement, the CFO of Anthropic revealed that its revenue run rate had exceeded US$47B annualized. For context, in January 2025, that figure was approximately US$1B. In 16 months, Anthropic multiplied its revenue by 47X. No technology company has ever done anything similar in that amount of time.
With its Series H closed, Anthropic surpassed OpenAI’s valuation for the first time, with an additional detail that many overlooked: the company confidentially filed its S-1 with the SEC just days after the round closed. The largest round in its history could also be its last before its public-market debut. The clock is already ticking.
3. Capital Is Becoming a Commodity
In January 2023, headlines reported that Microsoft had invested US$10B in OpenAI. What those headlines didn’t explain is that this investment was structurally different from any other on the list. The value didn’t come in cash, but in computing credits: access to Azure servers, supercomputing at scale, and the ability to train models that would otherwise have cost billions of dollars in their own infrastructure.
This wasn’t an accounting quirk. It was one of the largest and most prominent examples of an investment model that is now becoming a global trend: equity in exchange for services. One example of this model is Media For Equity, or M4E. In this arrangement, investors contribute strategic assets rather than cash—such as visibility, infrastructure, or audiences—in exchange for an equity stake. What Microsoft did with Azure and OpenAI has a direct conceptual parallel with what specialized infrastructure or media investors such as MediaForGrowth, Nascent VC or ILB Media Ventures.
In a world where building technology is increasingly accessible, scarce assets include distribution, audience, and infrastructure. Whoever controls them has a competitive moat that can’t simply be “financed.” Microsoft understood this a few years ago. The rest of the market is understanding it now.
4. The Most Strategic Investor in the Top 10 Isn’t from Silicon Valley
When people talk about major AI investors, they name Sequoia, a16z, SoftBank, and Tiger Global. But there’s one player that appears at least three times in the top 10 VC rounds in history, without almost any media outlet explicitly pointing it out: GIC, Singapore’s sovereign wealth fund.
GIC co-led Anthropic’s US$30B Series G in February 2026 alongside Coatue. It participated in Anthropic’s US$13B Series F in September 2025. And it appeared again, once more as co-lead, in the US$65B Series H in May 2026. Along with its historic participation in Ant Group and other institutional rounds, GIC has quietly become one of the major builders of the global AI ecosystem.
What matters here isn’t just the frequency, but the depth. GIC isn’t diversifying across dozens of small bets. It’s concentrating capital in the same companies, round after round, increasing its stake as valuations rise. It’s the strategy of an investor seeking not quick liquidity, but long-term structural influence in the companies likely to define the digital economy of the coming decades.
5. Project Prometheus: A Mysterious and Significant Newcomer
There’s one name on the list with no recognizable logo, no website, no public product, and barely any media presence: Project Prometheus. With a US$10B round in April 2026, it’s the only company in the top 10 that isn’t publicly known or listed on any market.
Jeff Bezos founded it in November 2025 alongside Vik Bajaj, a former Google X executive. Its mission, according to Bezos himself, is to create a “general artificial engineer,” a radically new tool for designing physical objects, which he described as a “very modern version of CAD” applied to industries such as aerospace, semiconductors, automotive, and pharmaceuticals. It has nothing to do with robotics, he clarified, although the confusion was understandable given the profile of its first 120 employees, recruited from OpenAI, DeepMind, Meta, and xAI.
One of the most disruptive insights isn’t what the company does, but who is financing its growth: BlackRock and JPMorgan are appearing as round anchors. These are two traditional financial institutions that have historically operated as asset managers or lenders, not as direct investors in early-stage startups’ Growth VC rounds. Having major banks enter AI startup rounds as direct co-investors, without going through a VC fund as an intermediary, marks a structural break with the traditional venture capital model. It suggests Prometheus could become one of the world’s most valuable private companies in the coming years.
6. A Diverse Cap Table Is Also a Political Signal
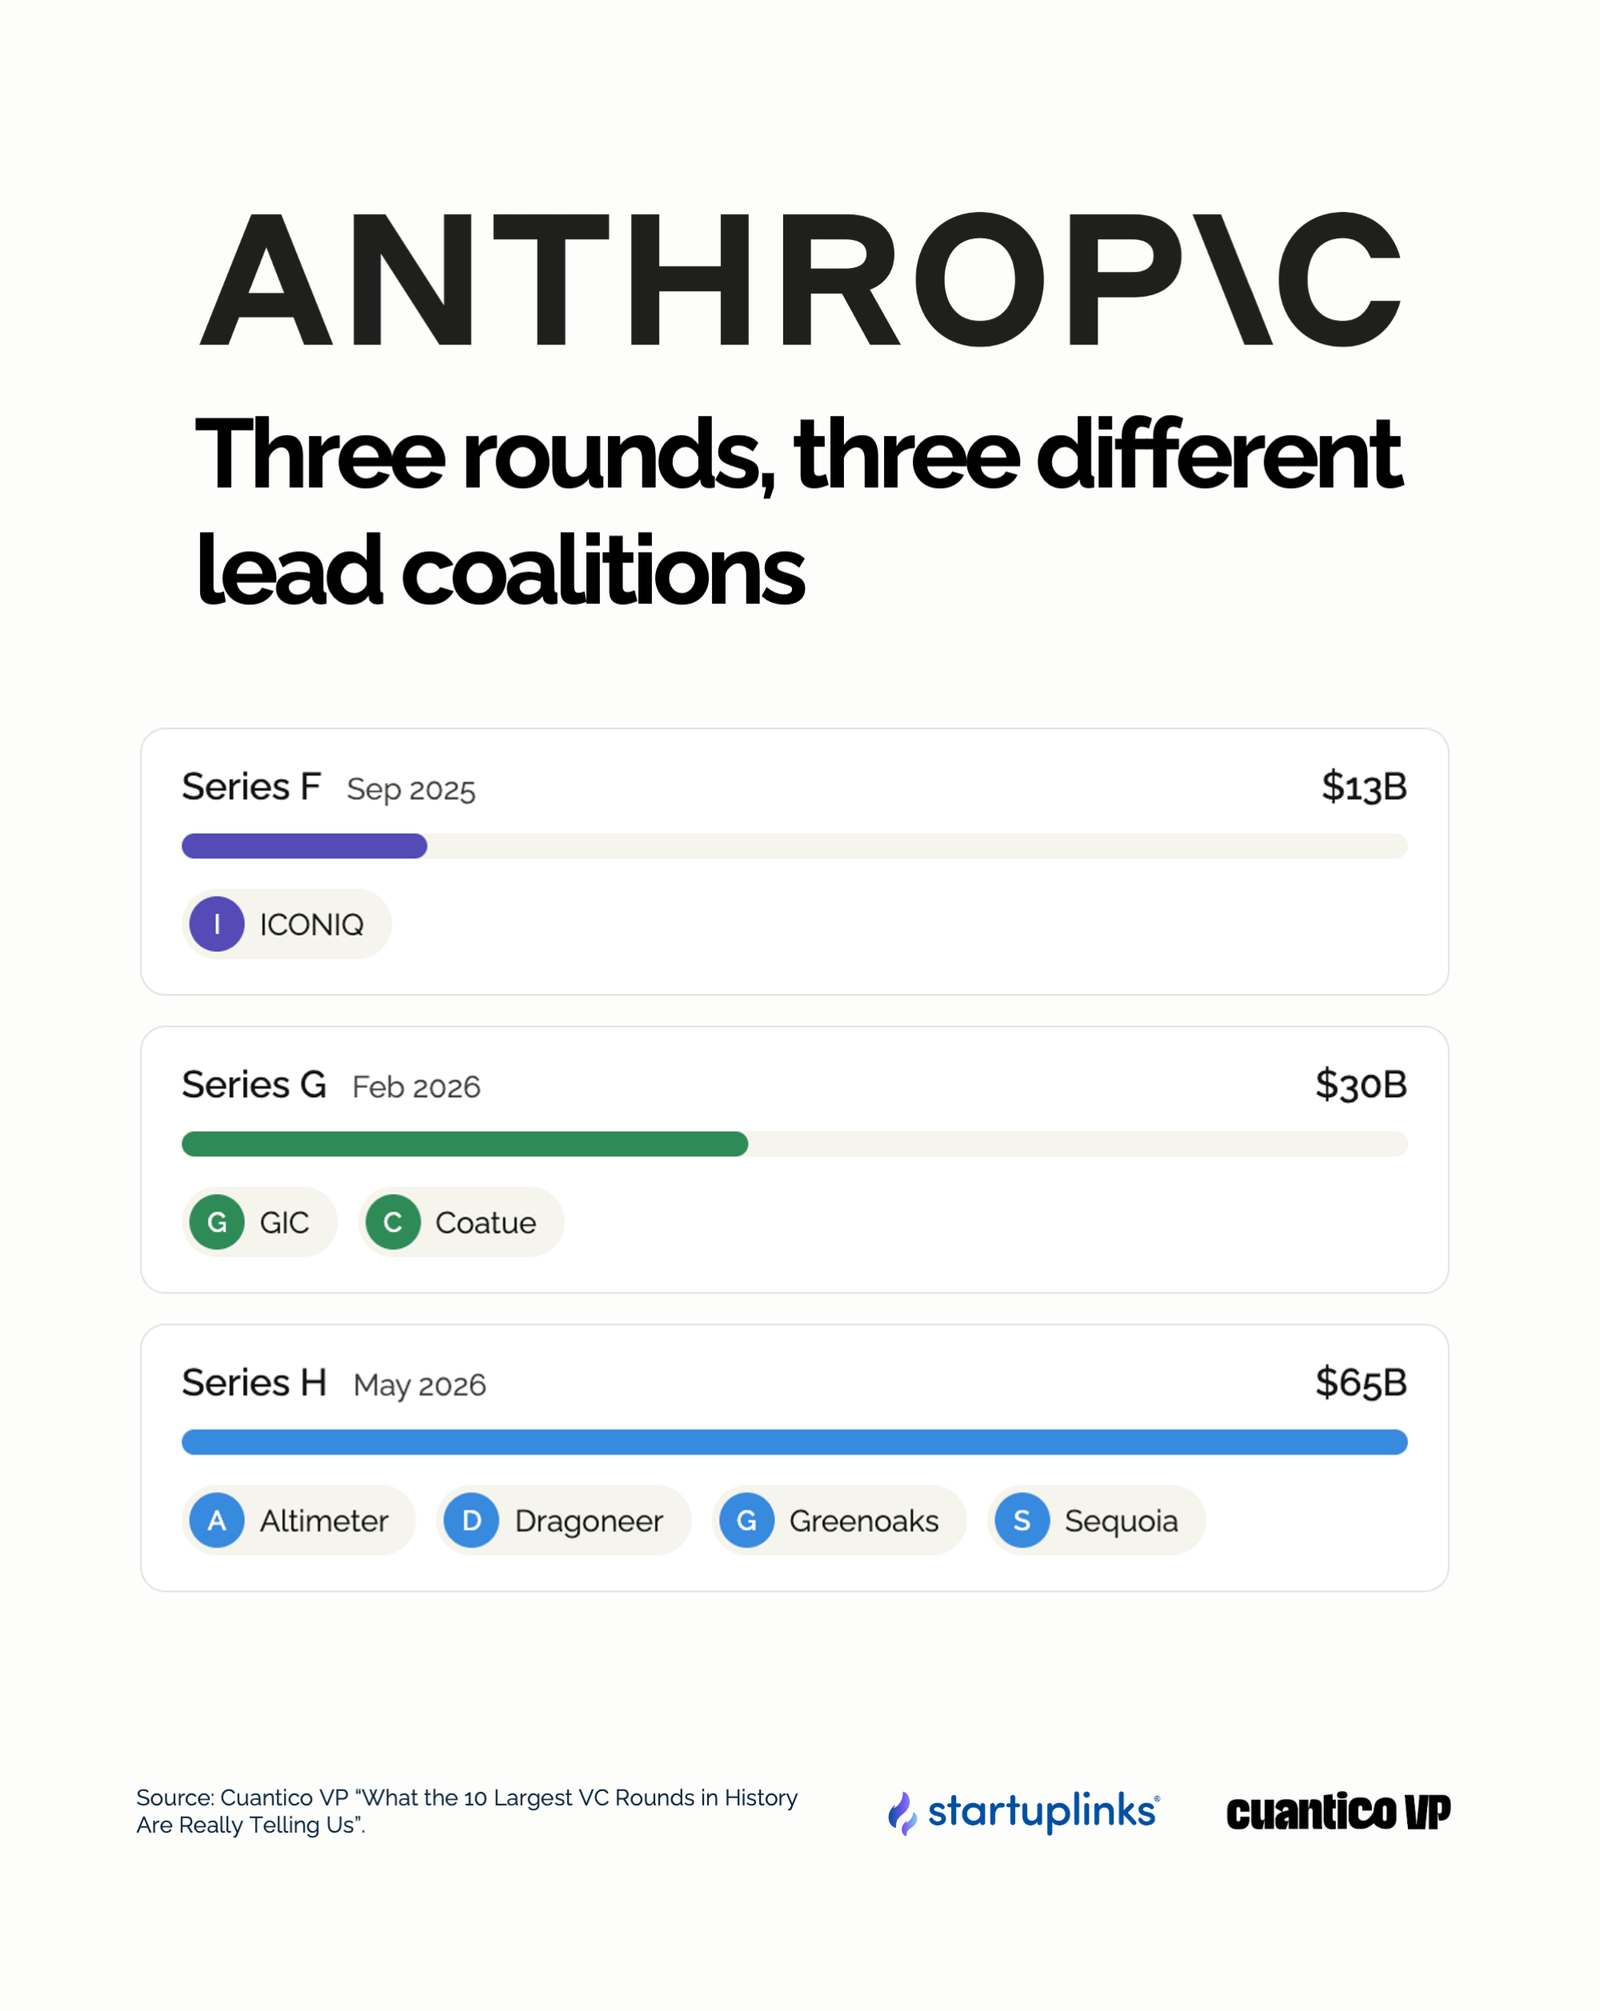
Anthropic appears three times in the top 10. That’s striking. But something is even more revealing: in each of those three rounds, the lead investor was completely different.
Series F (September 2025, US$13B): led by ICONIQ. Series G (February 2026, US$30B): led by GIC and Coatue. Series H (May 2026, US$65B): led by Altimeter, Dragoneer, Greenoaks, and Sequoia. Three rounds. Three different coalitions. No repeat lead investor.
It’s a completely different strategy from OpenAI’s, where Microsoft has been the dominant strategic anchor for years and SoftBank has emerged as the most significant institutional player in the last two rounds. Anthropic, by contrast, seems to have made a conscious decision not to have a single “patron.” That gives it strategic independence and operational flexibility, but it also means its governance is significantly more complex. When critical decisions arise, such as the IPO structure, commercial partnerships, or acquisitions, there isn’t a single player who can approve or veto them. There’s a table with many seats and voices. For now, that diversity seems to be a strength. The question is whether it will remain one when the tough decisions come.
7. The One Fact That Shows AI Isn’t a Classic Bubble: Revenue
Whenever headlines report billion-dollar valuations for companies that haven’t turned a profit, someone brings up the year 2000. And the comparison makes sense. But there’s one fact about the biggest AI rounds of the past 3 years that completely upends it: the revenue exists, and it’s real.
The dot-com bubble was built on promises of future revenue that never materialized, at a time when only 6% of the world’s population had internet access. Today, Anthropic disclosed in May 2026 an annualized revenue run rate of US$47B. OpenAI reported approximately $10B in actual revenue during 2025 and projects reaching US$100B or more in 2026. xAI closed US$20B in its Series E at a valuation close to US$230B, backed by computing infrastructure already deployed.
These aren’t projections of a hypothetical future. They’re current revenues growing at rates no technology company had ever recorded before. The difference between 2000 and 2026 isn’t one of degree, but of kind. So if it isn’t a bubble, what is it? It’s an accelerated concentration of economic power in a very small number of players. Depending on how you look at it, that may be more concerning than a bubble.
8. Geographic Concentration Is Nearly Total: 9 of 10 Rounds Are U.S. Companies
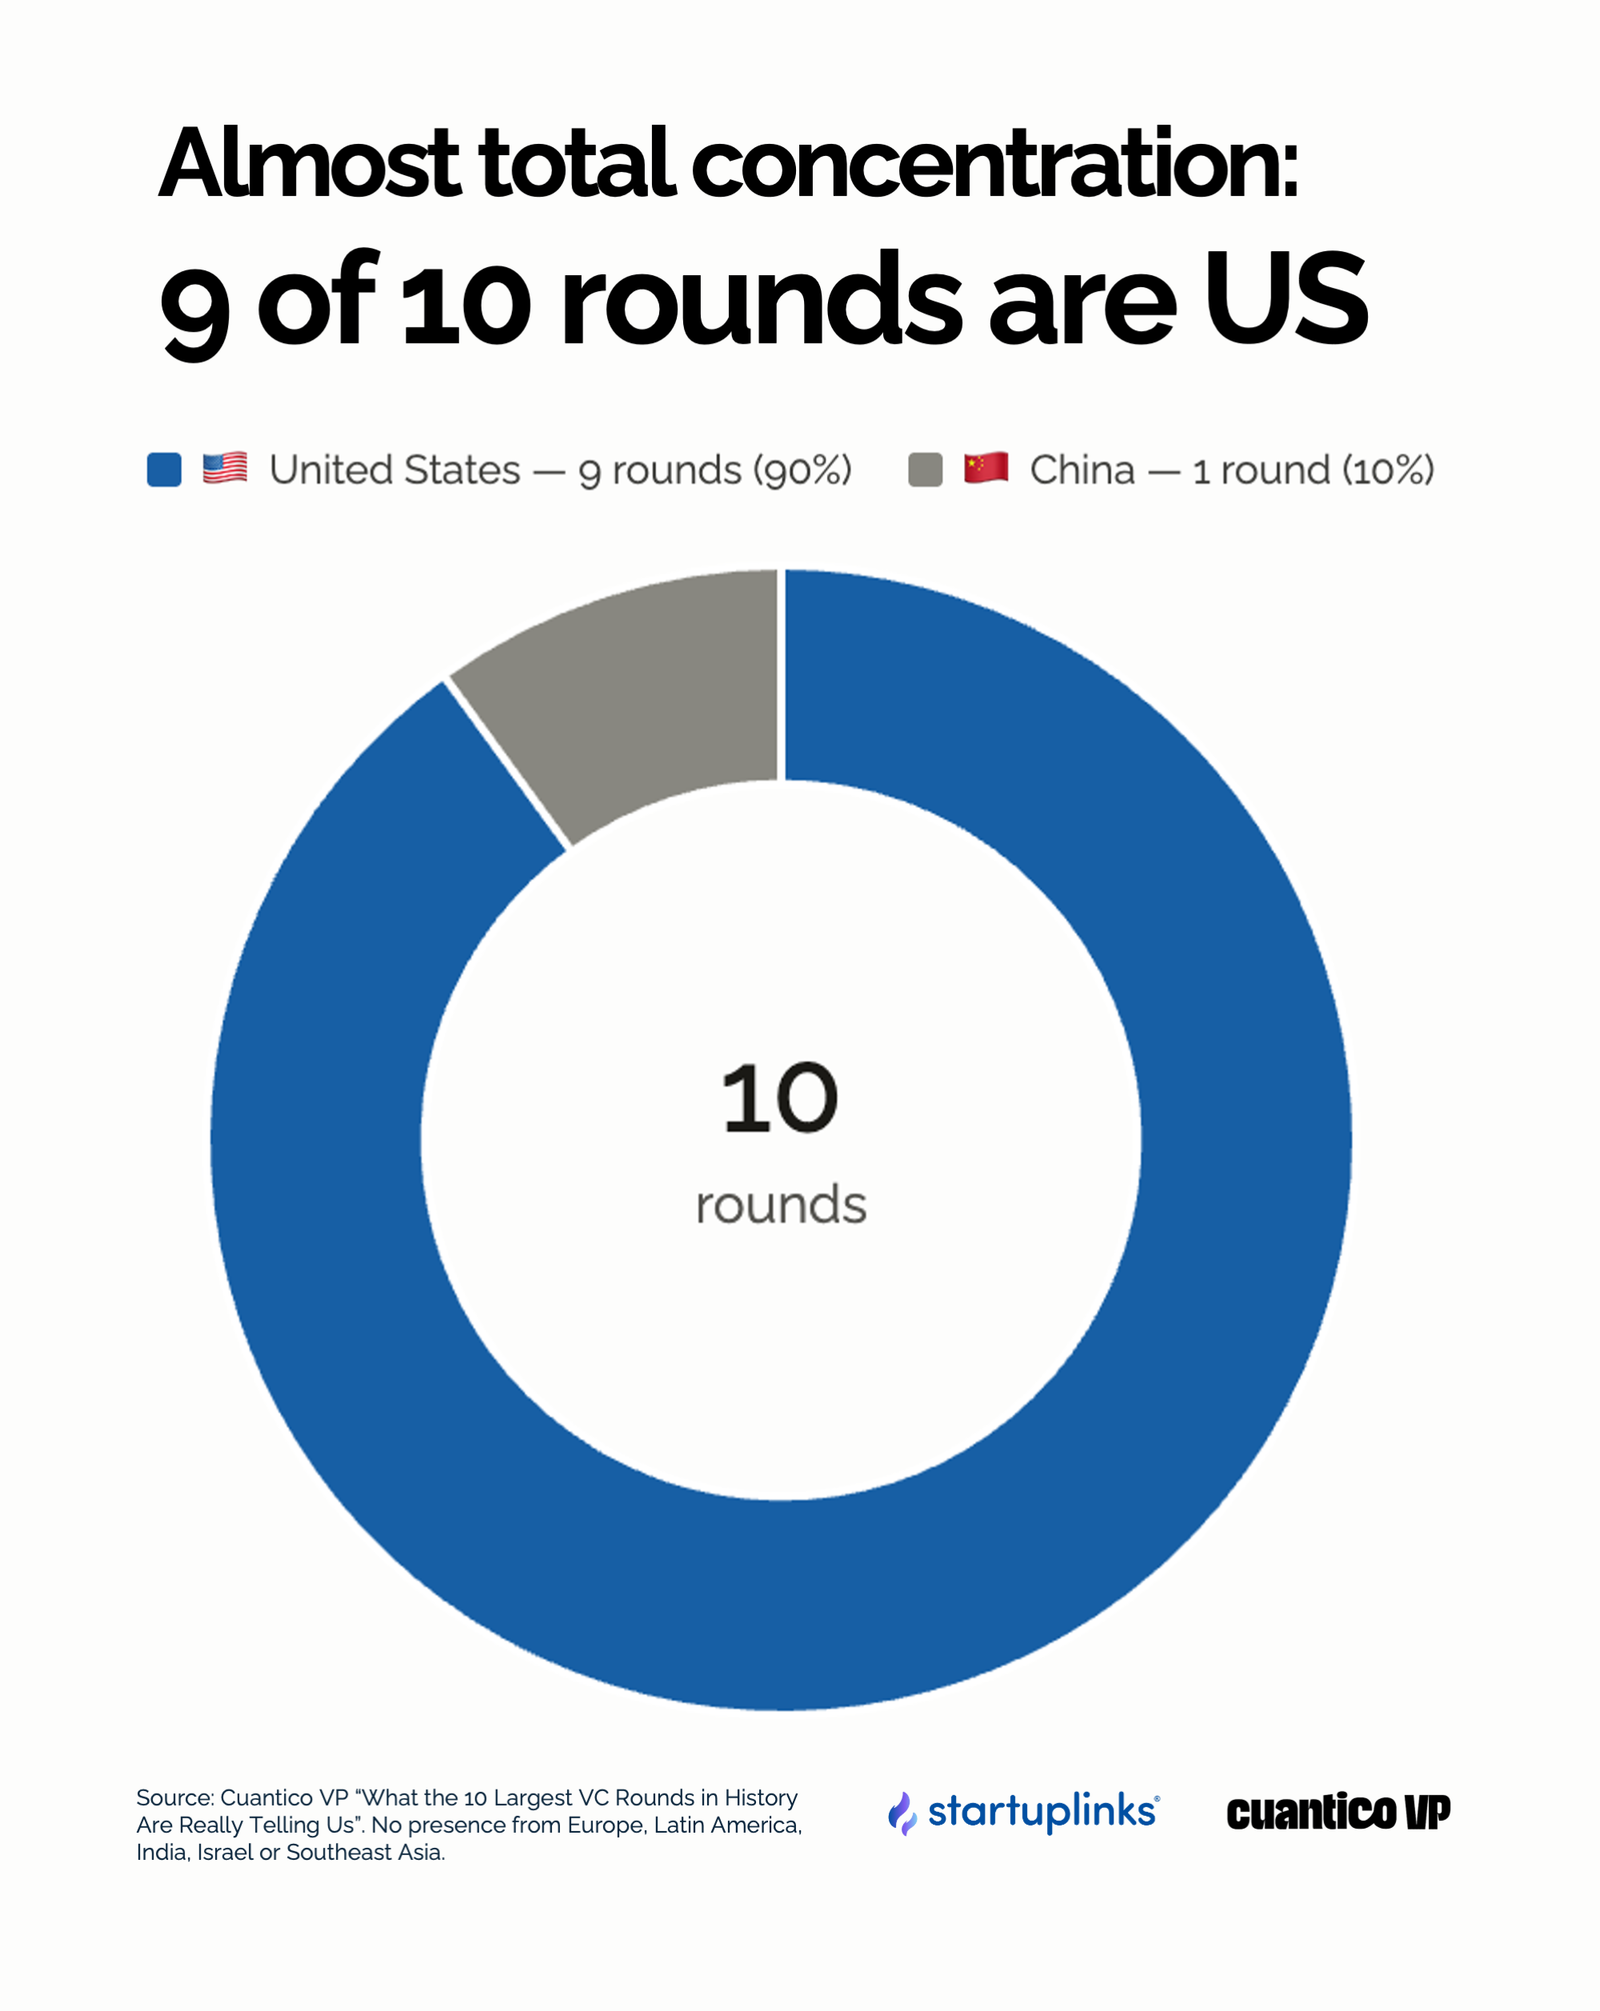
Of the 10 largest VC rounds in history, 9 went to U.S. companies. The sole exception is China’s Ant Group, in 2018. Not a single European company. Not one from Latin America. None from India, Israel, or Southeast Asia.
This isn’t a market accident. It’s the result of decades of ecosystem-building, capital and talent policies, and it’s now producing a concentration of technological power not seen since the early days of the internet. One notable feature of this concentration is where the capital has come from: Middle Eastern sovereign wealth funds like MGX and Qatar Investment Authority, Asian funds like GIC and Temasek, and European institutions like Baillie Gifford. Global capital is flowing to the United States instead of building competitive local ecosystems.
For emerging ecosystems like Latin America’s, the message is clear and urgent: available regional capital isn’t being deployed to build homegrown AI infrastructure. Every dollar an Asian or Gulf sovereign wealth fund invests in OpenAI or Anthropic is a dollar not being used to build an equivalent in Bogotá, Riyadh, or São Paulo. The concentration isn’t just technological. It’s geopolitical. And by the time local ecosystems want to compete, the gap may already be too large to close quickly.