Venture Capital Concentration and the Case of Mexico in 2026
There’s an issue that should be on the agenda of every investor, fund, and founder in the region, yet it continues to go almost unnoticed beneath the optimistic headlines: the extreme concentration of venture capital in Latin America and the United States. This isn’t a technical detail for data analysts. It’s an early
There’s an issue that should be on the agenda of every investor, fund, and founder in the region, yet it continues to go almost unnoticed beneath the optimistic headlines: the extreme concentration of venture capital in Latin America and the United States. This isn’t a technical detail for data analysts. It’s an early warning sign about the structural health of the entire ecosystem, and it deserves attention now—not when the problem has become irreversible. When two or three massive checks account for most of the reported capital in a market, the headline no longer reflects the reality of the startups being founded; it starts to obscure it. That’s exactly what’s happening today, and the consequences aren’t abstract: they determine which startups survive, which sectors go unfunded, and which cities in the region will still be producing founders five years from now.
In 2026, U.S. venture capital recorded a record first half, but the figure hides an uncomfortable reality: four massive AI financings account for most of the volume (OpenAI, Anthropic, xAI, and Waymo). Latin America is replicating this pattern, but with one critical difference. Its megadeals aren’t driven by a technological revolution like AI; they involve mature companies in sectors such as fintech seeking to consolidate positions they built a couple of years ago.
The case of Mexico: US$800M that are really three deals
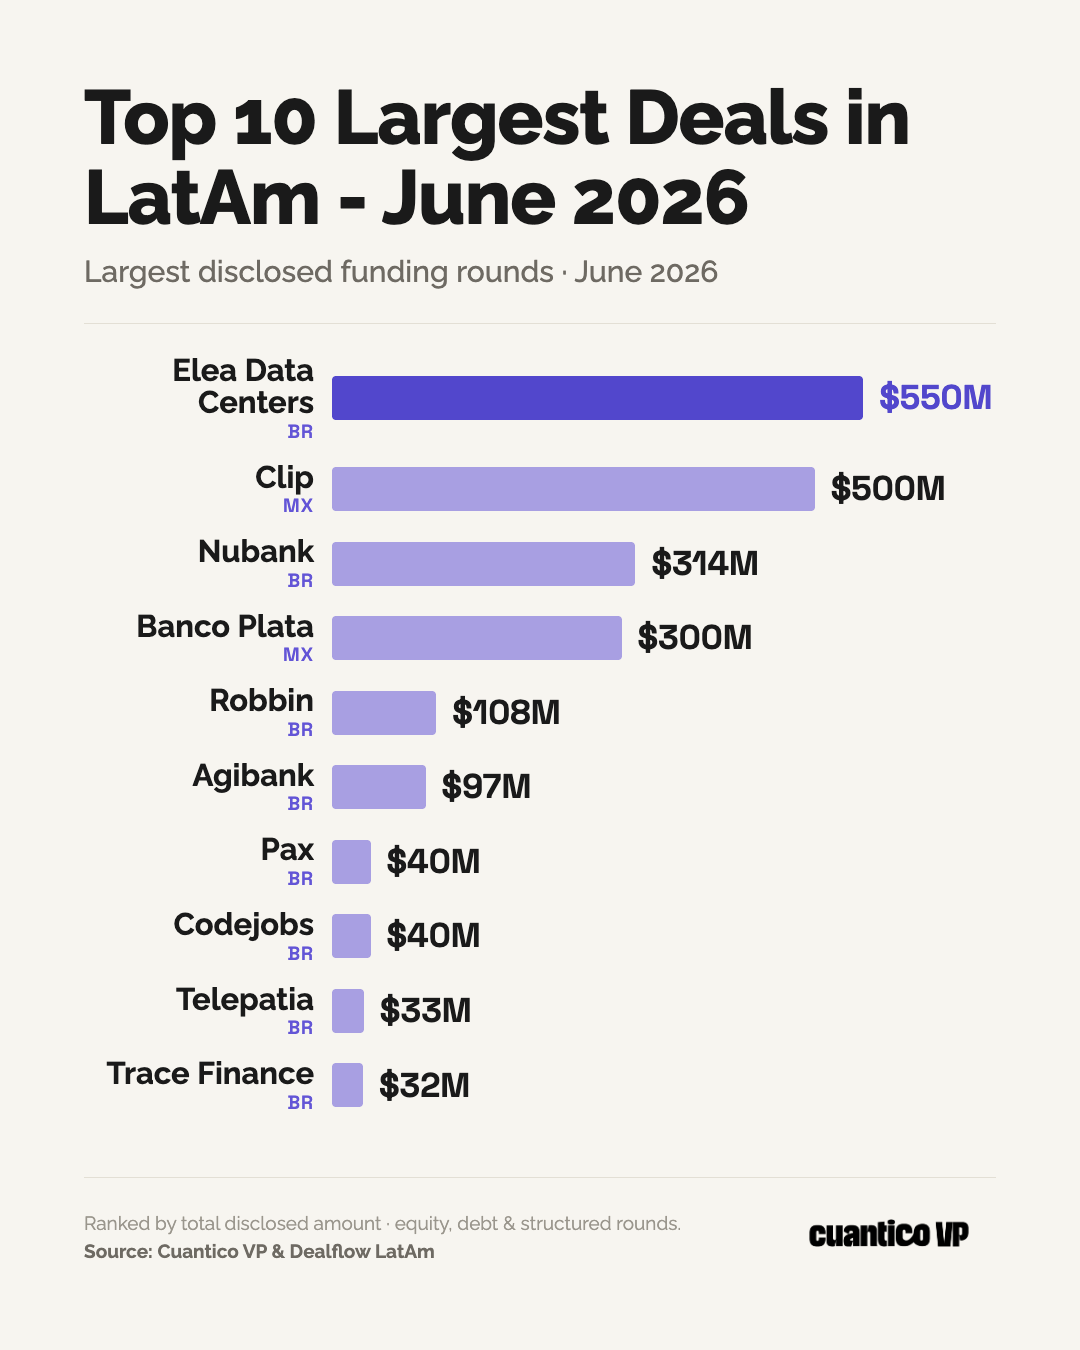
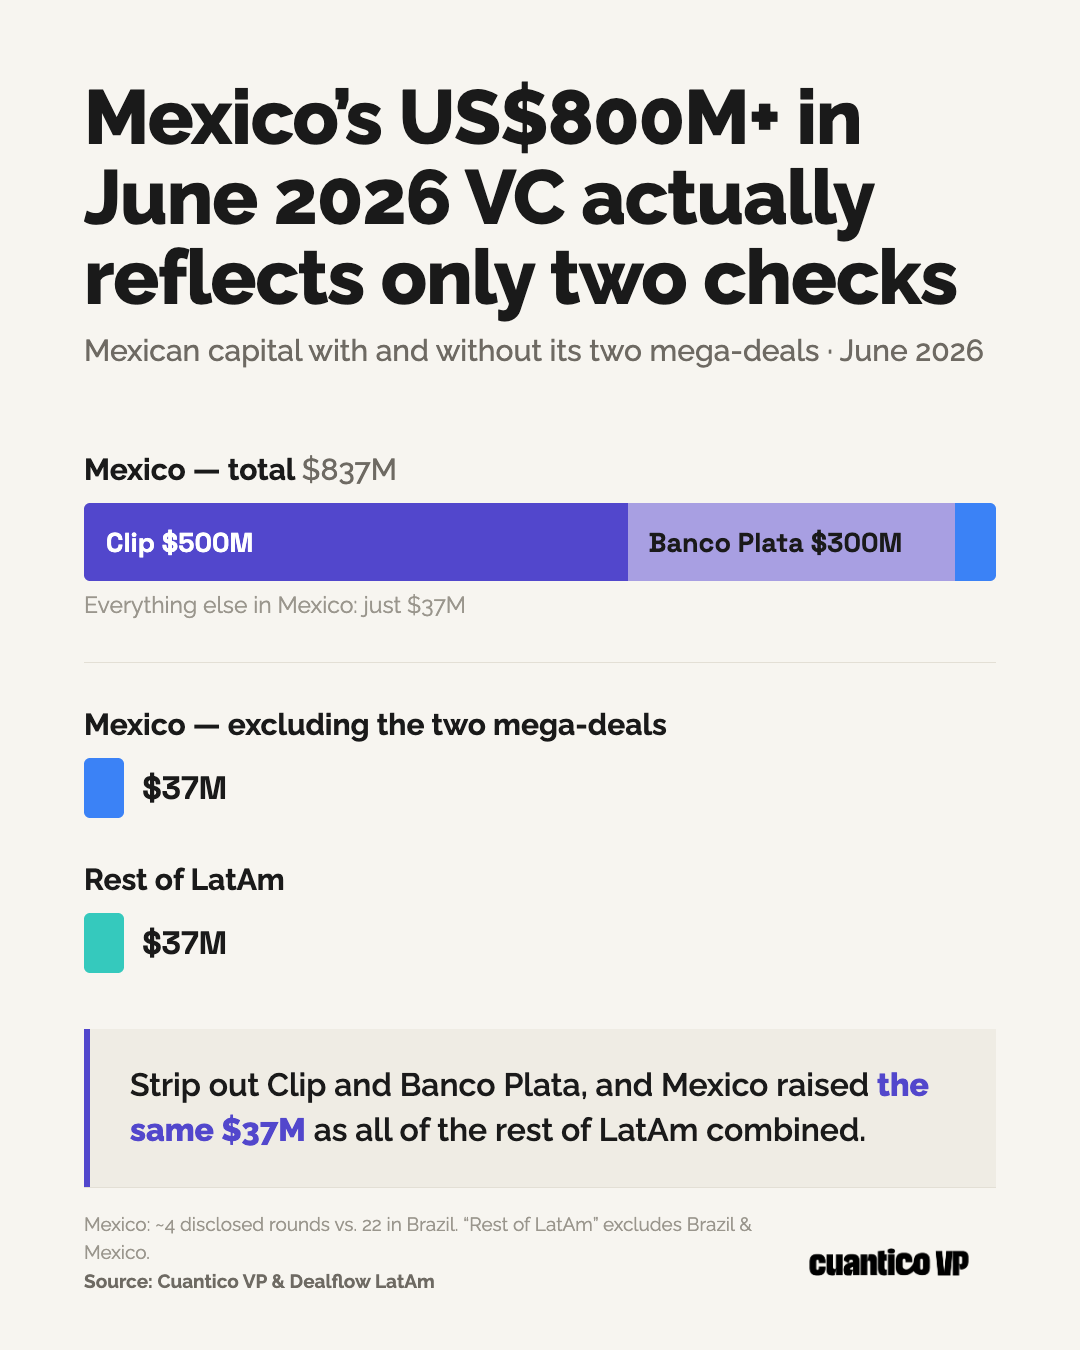
Mexico’s June 2026 metrics tell a perfect story about the statistical illusion of concentrated venture capital. The headlines say Mexican startups raised more than US$800 million during the month. The reality, once you look beyond the figure, is much more modest: Clip closed a US$500 million round, and Banco Plata expanded its credit line by an additional US$300 million. Two checks. One month. And all that’s left for the rest of the Mexican ecosystem is just US$37 million.
The figure that fully illustrates the distortion is that the same amount, US$37 million, was raised by the rest of Latin America (excluding Brazil and Mexico) during the same period. Without its two megadeals, Mexico doesn’t surpass much smaller markets in early-stage capital.
The regional picture: more capital, fewer startups
According to this year’s Latin America Venture Capital Report , in 2025 the Latin American VC ecosystem appeared to recover: more total capital than the previous year, but the number of rounds reached its lowest level since 2018. The average ticket size grew, confirming that more money is flowing to fewer startups with proven traction, rather than to a broader and more diverse ecosystem. Brazil and Mexico accounted for 70%+ of regional investment, and within those countries, capital was concentrated mainly in fintech companies with proven models.
The real problem: the pipeline is drying up
This is where the systemic risk over the medium and long term lies. The ecosystem is not only concentrating at the top of the funnel—Series B, Series C, and megadeals—but the very base of the funnel is collapsing. According to the study we published in collaboration with Cuantico VP, pre-seed funding fell in 2025, and the number of deals at that stage dropped by nearly 40% compared with the previous year, reaching its lowest levels across the entire period analyzed. Seed funding also saw a sustained decline in the number of rounds, despite a slight recovery in amounts. And 70%+ of investors identified the lack of exits as their main risk over the next 18 months.
The structural consequence is direct. If early-stage startups aren’t funded today, there will be no candidates for Series A in 18 to 24 months, or for Series B in 36 to 48 months. The pipeline isn’t a tap that can be turned on and off at will: it’s a sequential process in which each stage feeds the next. A gap at the base takes years to show up at the top, but by the time it does, it’s too late to fix.
The ecosystem’s long-term risks
Extreme capital concentration isn’t just a statistical distortion; it has concrete consequences:
- Sectoral homogenization. When fintech captures most of the capital with a fraction of the deals, sectors such as agtech, healthtech, climatetech, and edtech are left without oxygen. The ecosystem loses diversity and, with it, resilience to sector-specific shocks.
- One-city ecosystems. Geographic concentration in São Paulo and Mexico City deepens. Emerging ecosystems in Bogotá, Lima, Santiago, and Guatemala City are unable to retain founder talent or attract enough capital to build a critical mass locally.
- Dependence on foreign capital. Rounds like those of Clip and Banco Plata are financed mostly by international institutional capital. When global macroeconomic conditions change, that capital withdraws faster than it arrived. Ecosystems with a small base of local capital are the first to suffer.
- The “valley of death” widens. With fewer active early-stage funds in the region, the gap between pre-seed and an institutional Series A round is becoming increasingly difficult to cross. Many promising startups die along the way, not for lack of ideas, but for lack of bridge capital.
- A false signal for the ecosystem. Headlines like “VC hits a record in 2026” create a distorted perception of the market’s real state. Founders who read that figure without context may overestimate the capital available for their own rounds, misjudge their timelines, and make strategic decisions based on a reality that doesn’t exist for 95% of the market.
What the data really says
Venture capital in Latin America is showing maturity at the top: larger checks, more discipline, and a greater focus on unit economics. But the base is getting narrower. A healthy ecosystem needs at least three things: large rounds that build confidence, exits that demonstrate returns, and a steady flow of early-stage capital to replenish the innovation pipeline.
Today, the Latin American ecosystem has the first sporadically, while the second and third are in sustained decline. Two megadeals in Mexico in a single month aren’t a sign that the ecosystem is healthy across the board. They show that the ecosystem still needs to evolve.