Cashea demonstrates fintech’s potential in emerging markets with a US$100 million funding round
Cashea raised US$100 million across two funding rounds after building a BNPL platform that now reaches 35% of Venezuelan adults.
Cashea closed a US$100 million investment through two funding rounds, demonstrating that investors continue to bet on opportunities in underserved markets. Founded in Caracas in 2022 by Pedro Vallenilla, the buy now, pay later (BNPL) platform has achieved nationwide scale while operating in one of the world’s most challenging economies.
Cashea closes two funding rounds totaling US$100 million
The company completed its financing in two stages during 2026. In March, it closed a US$40 million Series A, with funding provided by Architect Capital and led by Spice Expeditions. Three months later, it secured a US$60 million Series B led by FinSight Ventures, with participation from Endeavor Catalyst and several Latin American venture capital funds.
Beyond the amount raised, the deal reflects investors’ confidence in a company that has already achieved significant operational scale in a market long considered too risky for much of international capital.
A BNPL model designed for Venezuela’s financial reality
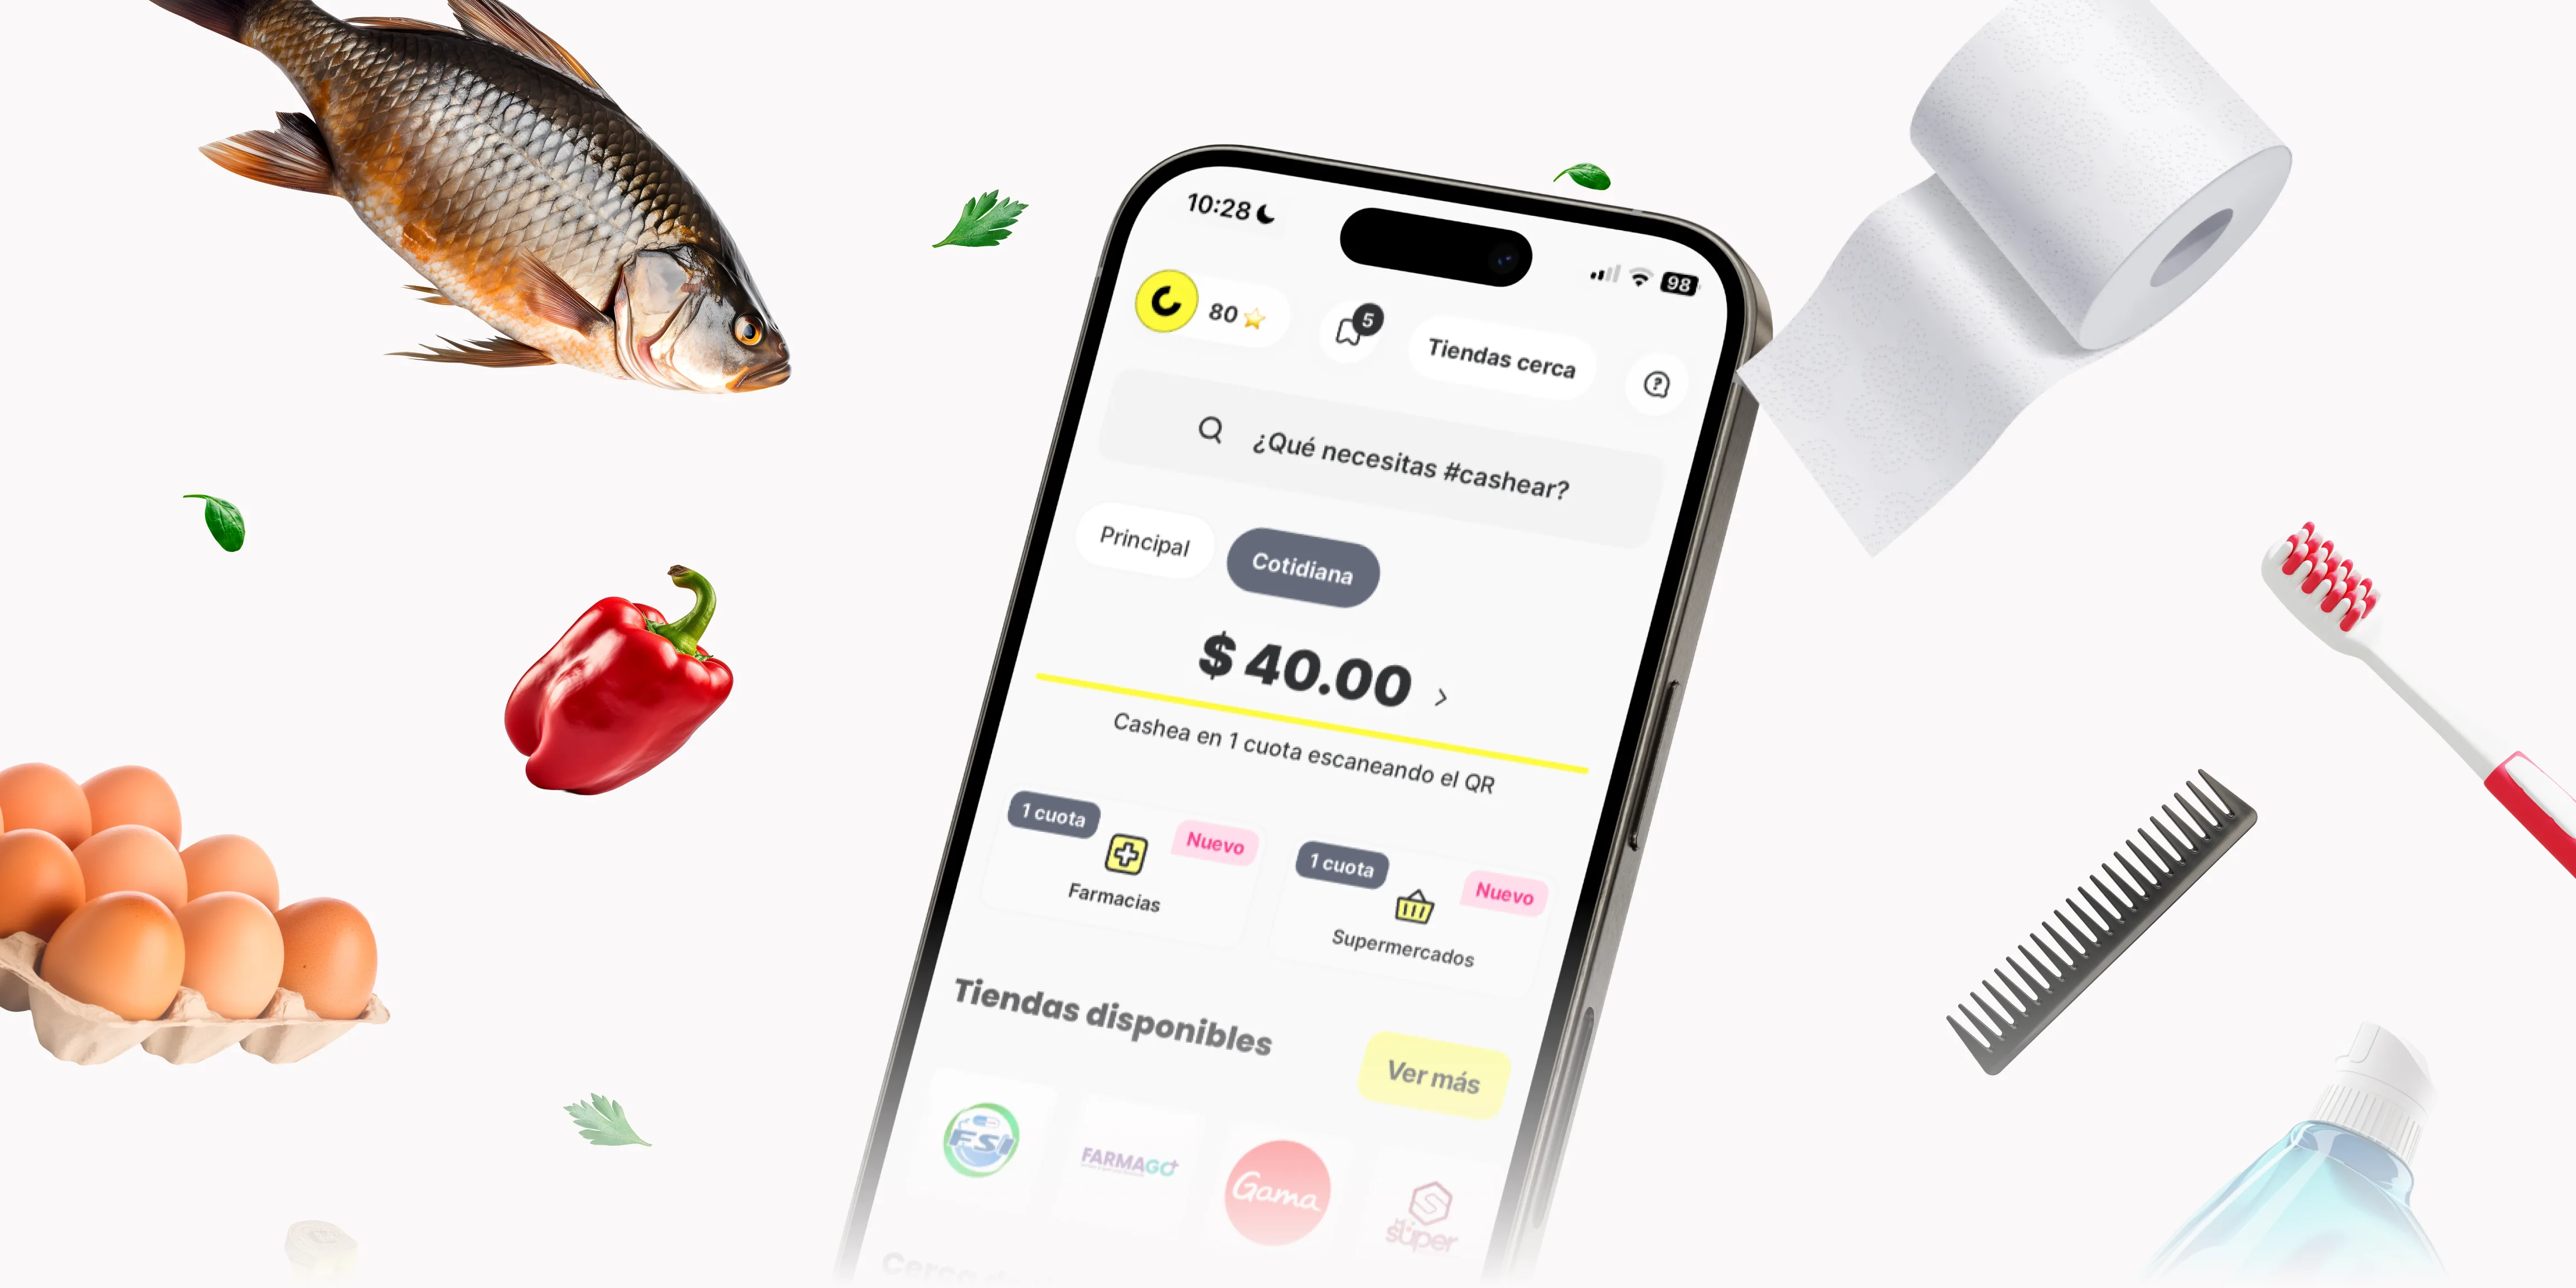
Cashea allows consumers to buy products in interest-free installments through a mobile app that connects shoppers directly with merchants.
Rather than relying on traditional banking infrastructure, the platform operates under a different model. Merchants themselves extend credit to their customers, while Cashea provides the infrastructure that supports each transaction and protects against potential defaults. Consumers pay for their purchases gradually, merchants receive their money, and Cashea earns revenue through transaction fees without charging users interest.
This model enables transactions to take place without any of the parties relying on a bank.
How Cashea achieved nationwide scale
Instead of trying to rebuild Venezuela’s banking system, weakened after years of economic crisis, Cashea developed an alternative infrastructure based on its relationships with merchants.
The platform currently works with more than 3.500 merchants across more than 25 cities, a network that drives both distribution and the generation of transaction data. According to the company, Cashea now reaches approximately 35% of Venezuela’s adult population, processes more than one transaction per second, and manages a transaction volume equivalent to more than 3% of Venezuela’s gross domestic product (GDP).
Another important indicator is its credit performance. The company reports a delinquency rate below 2%, reflecting how its growth has been accompanied by disciplined risk management.
The deal comes amid changes in the BNPL industry

Cashea’s round comes as BNPL companies face a more demanding regulatory environment in major international markets.
During 2025 and 2026, regulators in the United States, United Kingdom, and European Union tightened rules on installment loans, introducing more stringent affordability checks and credit reporting requirements for companies such as Klarna and Affirm.
Venezuela remains outside that regulatory process, creating a different landscape. On the one hand, companies face fewer compliance requirements; on the other, they operate amid greater country risk and a more limited legal infrastructure.
In this context, Endeavor Catalyst’s participation alongside Latin American funds suggests that a growing number of investors see fintech companies in emerging markets as financial infrastructure rather than highly speculative bets.
Another notable aspect is the company’s level of market penetration. Cashea says it reaches 35% of the country’s adult population, a figure few BNPL companies in developed economies have achieved, mainly because the company entered a market where formal credit had all but disappeared.
Lessons for entrepreneurs and investors
Cashea’s growth offers several lessons for those looking to build companies in markets with low financial inclusion.
Large market gaps can become opportunities
Rather than competing with established financial institutions, Cashea entered a market where formal credit had all but ceased to exist. Meeting that need allowed the company to grow without facing significant competition.
Leveraging existing networks can accelerate growth
Instead of building direct relationships with millions of consumers, the company leveraged its network of more than 3.500 partner merchants. While merchants maintain relationships with their customers, Cashea provides the infrastructure, protection against defaults, and settlement of transactions.
Portfolio quality remains the key indicator
Although user growth is important, one of the company’s strongest metrics is its delinquency rate of less than 2%. Maintaining solid credit performance has been key to demonstrating the sustainability of its business model and attracting institutional investors.
Complex markets can also become competitive advantages
The same economic conditions that deter many investors also limit competition. Companies able to operate successfully in these environments can develop capabilities that are difficult for new entrants to replicate.
A fee-based model can offer greater sustainability
Cashea earns revenue through fees charged to merchants rather than generating returns from interest paid by consumers. This approach aligns its model with those who directly benefit from each sale and avoids some of the regulatory and affordability pressures facing other BNPL models in different markets.